LATAM’s Oil & Gas Market: What International Energy Companies Need to Know Before Moving In
LATAM produces 3.4 million barrels of oil per day more than any other country in Latin America. The pre-salt basin holds reserves that rival the North Sea. And yet most international energy companies are still working out how to hire a single person here compliantly
Author: Wide LATAM
Apr 24, 2026 | 6 min read
Categories
Shell, TotalEnergies, Equinor, and BP didn’t wait for LATAM’s market to mature before building local teams. They moved while the pre-salt was still ramping. That positioning now gives them access to ANP licensing rounds, Petrobras supply contracts, and a talent pipeline that took years to build. Catching up from zero is possible but it takes longer than most companies budget for.
Petrobras’s 2024–2028 capital plan allocates $102 billion in upstream investment. Much of that flows through supply agreements that require local registration and track record. Companies without a LATAM presence can’t bid. That’s not a regulatory technicality, it’s a hard commercial exclusion.
The market in numbers
LATAM ranks in the global top 10 for proven oil reserves: 15.9 billion barrels, concentrated in the Santos and Campos basin pre-salt fields. Production hit 3.4 million barrels per day in 2025, up 7.8% year-on-year. Nothing else in Latin America comes close Mexico produces 1.8 million bpd, Colombia 0.8 million.
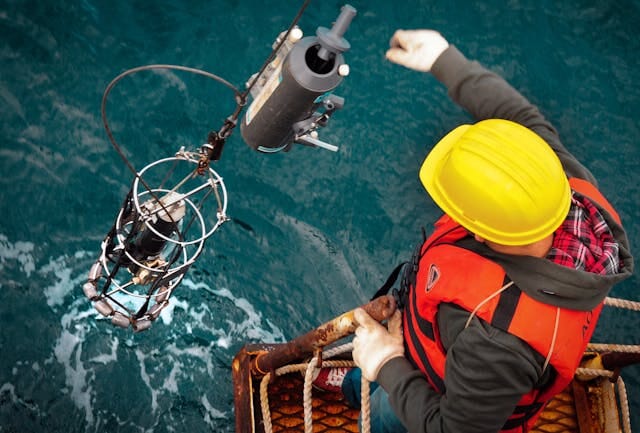
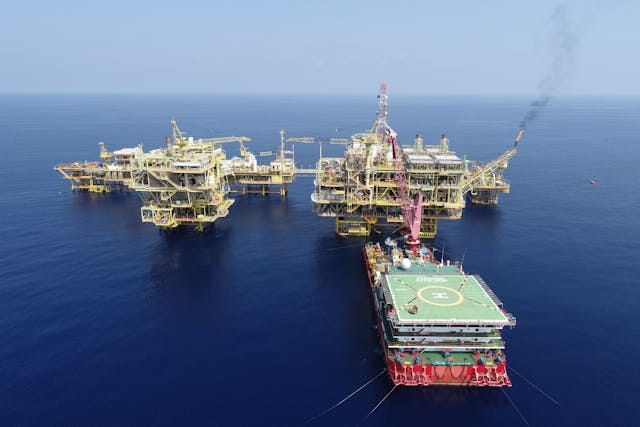
95% of that production is offshore. Deepwater and ultra-deepwater. That single fact shapes everything downstream: the talent profiles you need, the certifications required, the cities where those people actually live, and the compliance structures that apply.
The main operational hubs are Rio de Janeiro Petrobras HQ, the Campos Basin operations center, Macaé’s offshore services cluster 180km up the coast and São Paulo, which anchors the Santos Basin and houses most international operators’ commercial offices. Payroll and compliance structures differ between states. Where you hire matters.
Why local presence is not optional
Some sectors let you service LATAM from abroad for a while. Upstream O&G is not one of them.
ANP licensing rounds require local registration and a demonstrated track record. No LATAM presence, no bid. Petrobras supply contracts carry local content thresholds miss them and you face contractual penalties that can wipe out project economics entirely. The New Gas Law opened midstream to private competition, but accessing those opportunities still requires entities, relationships, and people on the ground.
On hiring: the offshore and subsea talent pool in LATAM is genuinely deep over 400,000 direct and indirect jobs across the sector. ROV pilots, FPSO operations engineers, NR-33/NR-35 certified HSE officers, reservoir engineers, rope access teams (IRATA L1–L3). These people exist and they’re findable. But operators who can move faster are absorbing them. A LATAM HR and recruitment infrastructure is not a nice-to-have at this point.
What makes hiring in O&G LATAM different from other markets
Most international companies do the cost comparison correctly but miss the compliance complexity underneath it.
LATAM professionals must be hired under CLT the formal labor code that adds 60–75% on top of base salary in statutory costs across all roles. That number doesn’t flex based on sector. Getting it wrong means retroactive liability from the start date of the relationship.
International specialists working in LATAM need valid work authorization before they set foot on a platform or an industrial site. For technical specialists: a VITEM V technical visa. For rotational offshore workers: the Offshore Visa. Neither is quick without someone who knows the process. Deploying an international specialist without the right documentation creates exposure under both labor law and immigration regulations simultaneously.
Many offshore roles carry mandatory certifications HUET, OPITO BOSIET, NR-33, NR-35. Operators require them. Petrobras requires them. Sourcing pre-certified candidates rather than hiring and then discovering the gap is the difference between a smooth mobilization and a delayed one.
One more thing worth flagging: most O&G projects in LATAM need both tracks at once. LATAM nationals under CLT, international specialists under visa and fiscal structures. Coordinating those two populations across separate vendors creates gaps in compliance, in billing, in accountability when something goes wrong. Managing both under one local partner removes that complexity.
What LATAM’s talent pool actually looks like
São Paulo and Rio produce deep benches of offshore engineers, subsea technicians, and drilling professionals. The comparison to equivalent North Sea or Gulf of Mexico profiles holds up: LATAM specialists run at roughly 50% of the cost for comparable experience and certification levels. That’s why Schlumberger, Halliburton, and Baker Hughes built full LATAM entities here rather than trying to service the market from outside.
Roles that international companies consistently need and that LATAM’s market produces well: offshore installation managers, toolpushers and drillers, subsea engineers, NDT/UT/MPI inspectors, pipeline and structural engineers, local content specialists, regulatory affairs managers. The profiles are there. The gap is usually the recruitment infrastructure to reach them efficiently.
How to start without an entity
Incorporation in LATAM takes 3–6 months and creates ongoing compliance overhead before a single contract is signed. For most international companies entering O&G, that timeline doesn’t match the commercial reality projects don’t wait for entity setup.
Employer of Record is the practical starting point. An EOR employs LATAM professionals under full CLT compliance ,FGTS, INSS, 13th salary, all of it while running visa processing and fiscal regularization for international specialists in parallel. No incorporation required. First hire onboarded within days of contract signature.
When the operation scales to the point where a local entity makes commercial sense because ANP requires it, because Petrobras contract terms demand it, because volume justifies it the transition from EOR to your own LATAM entity doesn’t require rebuilding the team. The people stay. The structure changes underneath them.
We put together a detailed market guide covering LATAM’s O&G talent landscape, regional dynamics, compliance structure, and how to build a workforce across both CLT and international specialist tracks. Download the O&G Market Guide →
OUR SERVICES